


Quality determines what we want to own. Valuation helps us decide when to act.
Welcome to this week’s MP Market Review, where we put our dividend growth investing (DGI) process into practice with real money, real positions, and real results.
Our monthly Timely Ten, which ranks the most undervalued dividend growth companies on our Canadian and U.S. watchlists, remains one of our most-read features. This month, a few high-quality companies have become more attractively valued, creating potential opportunities for investors looking to initiate or add to positions.
For paid subscribers seeking more guidance, our DGI Alerts reveal what we are buying and selling in our model portfolios and why. The final decision is always yours.
We do the work. You stay in control.
IN THIS ISSUE: DGI Clipboard • DGI Scorecard • DGI News • DGI Updates • Earnings Releases
DGI Clipboard
“Current yield, using its own historic yield as a guide, is, in my view, a fine valuation measure.”
— Tom Connolly
Timely Ten: When Quality Stocks Fall, We Pay Attention
Timely Ten Update
Little changed in either our Canadian or U.S. Timely Ten this month, which is not surprising given that markets traded mostly sideways. Beneath the quiet surface, however, several meaningful valuation shifts caught our attention.
The Canadian list remained largely intact, although a few companies moved significantly within the rankings. South of the border, two stocks dropped off the list, making room for two new entrants.
This month, we examine the biggest movers, the reasons behind their recent price weakness, and whether these emerging valuation signals warrant further research.
How We Rank the Timely Ten
Each month, we rank every company on our Canadian and U.S. watchlists by the discount between its current market price and its estimated fair value, using Dividend Yield Theory.
The calculation is straightforward:
Fair Value = Current Annual Dividend ÷ Historical High Dividend Yield
The larger the discount to estimated fair value, the higher the company ranks.
The ten companies above the thick black line are trading below their estimated fair values and currently offer dividend yields above their historical high yields.
These are our Timely Ten.
No valuation method is perfect, but Dividend Yield Theory has proven an effective way to identify attractive entry points into high-quality dividend growth companies. Combined with our quality-first investment process, it helps us deploy capital with greater discipline and removes much of the emotion from our decisions.
The Timely Ten is not an automatic buy list. It is a starting point for further research.
Canadian Timely Ten
#1 Couche-Tard
Couche-Tard remains firmly entrenched at the top of the Timely Ten following a 12.5% pullback in its share price.
The company delivered a strong first quarter, with revenue increasing 25.1%, adjusted EBITDA rising 10.5%, and adjusted diluted EPS advancing 15.4%. Stronger fuel margins, acquisition contributions, and continued organic growth in the convenience business supported the results.
Despite this solid operating performance, the shares have remained under pressure. One possible concern is the proposed $8.6 billion acquisition of Żabka Group, which would significantly expand Couche-Tard’s presence in Central and Eastern Europe. The transaction is expected to be financed using available cash and new and existing credit facilities.
Although the earnings report does not attribute the share-price weakness to the transaction, its size may be contributing to investor caution. With the underlying business continuing to perform well, the recent pullback may soon provide an opportunity to add to our position.
#2 Canadian Tire
Canadian Tire made one of the biggest moves this month, climbing from #4 to #2 as recent price weakness improved its valuation.
Its latest quarter was solid, with normalized EPS increasing 10.4% and return on invested capital improving. However, dividend growth has been minimal in recent years, making us less likely to initiate a position.
Investors focused primarily on capital appreciation may find the shares attractive at this valuation. For dividend growth investors, however, the limited growth in income remains an important consideration.
#3 Waste Connections
Waste Connections remains on the podium at #3.
As one of the highest-quality companies on the Timely Ten, it always warrants attention when its valuation becomes more compelling. The latest quarter reinforced that quality, with revenue increasing 6.4%, adjusted EBITDA rising 6.8%, and margins continuing to expand. Management also raised its full-year 2026 outlook.
Strong free cash flow, continued acquisition activity, and record year-to-date share repurchases further support the company’s position in our Canadian model portfolio.
Waste Connections may not be deeply undervalued, but opportunities to purchase businesses of this quality at a sensible price are always worth investigating.
#5 Stella-Jones
Stella-Jones moved up two positions, from #7 to #5, as recent price weakness improved its relative valuation.
While Canada-U.S. trade uncertainty remains a consideration, the second-quarter results suggest the more immediate concern is margin pressure rather than revenue deterioration. Sales held relatively steady at $1.04 billion, supported by continued strength in Utility Products. However, adjusted EBITDA margin declined to 16.0% from 18.3%.
Higher operating and fuel costs, inefficiencies in the steel-structure business, and delayed pricing recovery all weighed on profitability. Residential lumber sales also declined 5%, reflecting lower lumber prices, softer demand, and unfavourable weather.
Management expects margins to improve during the second half, although full-year adjusted EBITDA margin is now expected to remain below 17.5%. Further research is warranted, particularly around tariff exposure and the potential impact on the residential lumber business.
#6 Metro Inc.
Metro Inc. remains interesting despite slipping from #2 to #6 while its share price remained relatively flat.
The current ranking appears largely tied to near-term headwinds, particularly the ongoing labour conflict at its Laval distribution centre. The disruption reduced third-quarter earnings by an estimated $0.32 per share.
Food same-store sales declined 1.5%, but pharmacy remained a source of strength, with same-store sales increasing 4.8%. With the labour disruption continuing into the fourth quarter, some near-term pressure is likely to remain.
The key question is whether these challenges are temporary or signal a more lasting deterioration in the business. For now, the underlying company continues to show resilience.
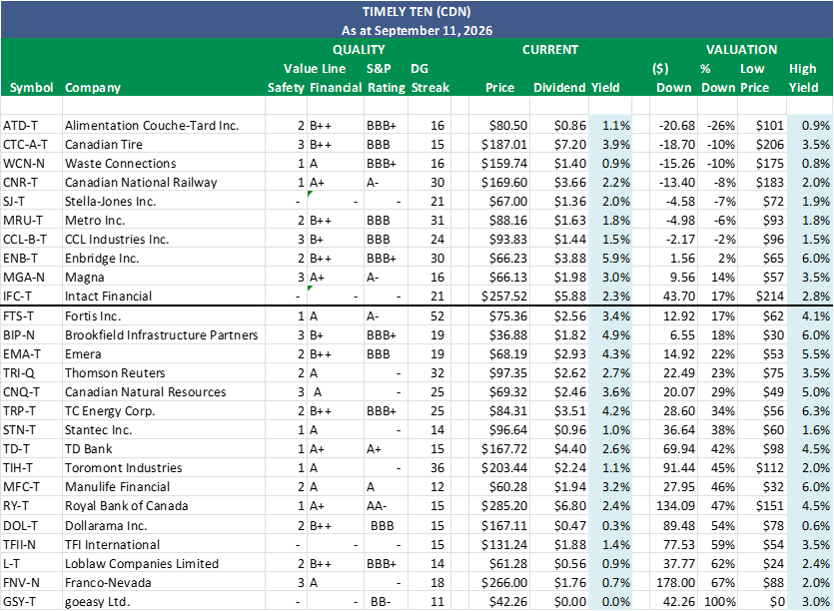
Note: goeasy Ltd.’s dividend has been suspended, so we have moved it to the bottom of the list.
American Timely Ten
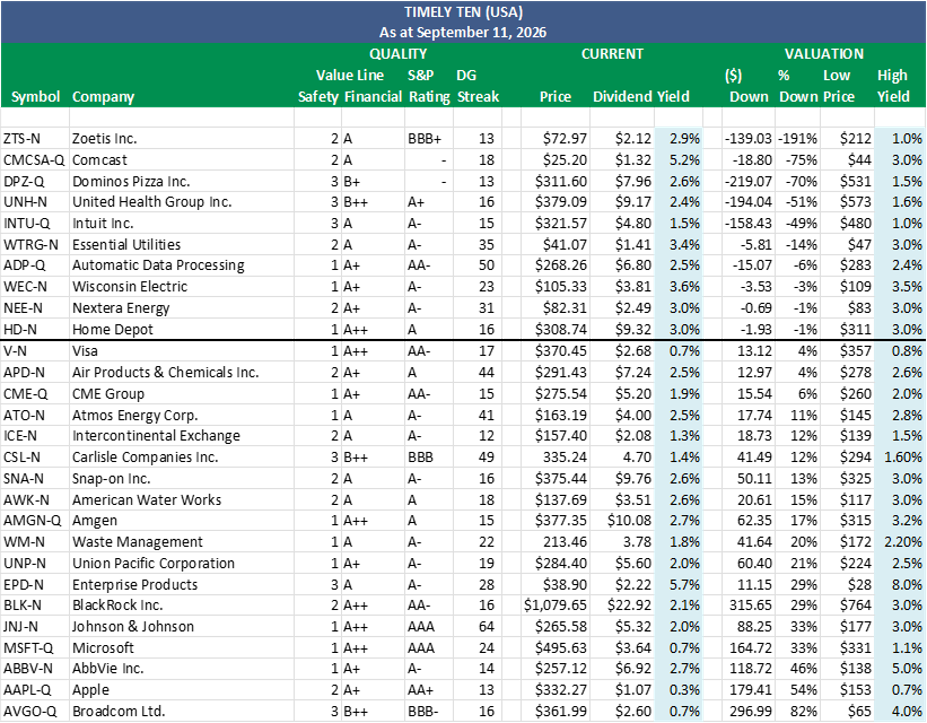
The most notable changes to the U.S. Timely Ten occurred near the bottom of the rankings. Two companies dropped off the list, allowing NextEra Energy and Home Depot to move into the #9 and #10 positions.
At the top, Zoetis remains the most undervalued company according to Dividend Yield Theory, although its recent results show why investors remain cautious.
#1 Zoetis
Zoetis remains the #1 undervalued American company based on Dividend Yield Theory for another month.
Its latest results help explain why the shares remain inexpensive. Second-quarter revenue was flat at $2.5 billion, while U.S. companion animal sales declined 11%. Management also materially reduced its full-year outlook amid weaker veterinary visits, affordability pressures, and increased competition.
The quarter was not without positives. Livestock sales grew 11%, diagnostics advanced 12%, adjusted EPS increased 4%, and Zoetis returned more than $550 million to shareholders through share repurchases.
With management expecting pressure in its key companion animal franchises to persist through the second half, I do not currently see a near-term catalyst that would displace Zoetis from the top of our valuation screen.
The valuation is becoming increasingly attractive, but investors may need patience while the companion animal business stabilizes.
#9 NextEra Energy
NextEra Energy is a new entrant to the Timely Ten at #9. It has been a strong investment since we added it to our American model portfolio almost three years ago.
Despite a mostly positive second-quarter earnings report, the shares have recently come under pressure as investors consider the prospect of higher interest rates and the uncertainty surrounding the proposed Dominion Energy merger.
Higher interest rates can weigh on capital-intensive utilities by increasing financing costs and making their dividend yields less attractive relative to bonds. The Dominion transaction introduces additional regulatory, integration, and execution risks ahead of its expected closing in the second half of 2027.
The recent weakness, however, appears more reflective of valuation and transaction-related concerns than deterioration in NextEra’s operating performance. The company continues to benefit from expanding regulated investment at Florida Power & Light, a substantial renewable energy and storage backlog, and growing electricity demand from large-load customers.
With earnings growth remaining on track and management maintaining its long-term outlook, the pullback has not altered the positive fundamental picture. Interest-rate sensitivity and the execution of the Dominion combination remain the most important risks to monitor.
#10 Home Depot
Home Depot enters this month’s Timely Ten at #10. As the highest-quality-rated company on the list, it immediately catches our attention.
The stock remains under pressure as investors weigh solid company execution against a challenging backdrop for housing and home improvement. Elevated interest rates, limited housing turnover, and consumer caution continue to restrict spending on larger renovation projects.
Fundamentally, Home Depot’s second-quarter results were encouraging. Management said the quarter exceeded expectations and reported broad-based demand, with customers continuing to spend on smaller projects.
The disconnect is relatively straightforward: Home Depot continues to produce solid results, but investors are waiting for clearer evidence that the home-improvement cycle is strengthening.
Key indicators to watch include customer traffic, larger-project activity, operating margins, and sustained acceleration in comparable sales and earnings. Until those improve, the shares may remain under pressure. For long-term investors, however, the opportunity to purchase a company of Home Depot’s quality at a more attractive valuation deserves further attention.
Takeaway
Sideways markets may produce little change at the index level, but they can still create meaningful opportunities beneath the surface.
Couche-Tard’s strong results have yet to overcome concerns surrounding its proposed acquisition. Canadian Tire and Stella-Jones have moved higher on valuation, but both come with important trade-offs. Waste Connections continues to demonstrate why quality deserves a place near the top of our process, while Metro’s current challenges appear primarily short-term.
In the United States, Zoetis remains inexpensive for identifiable reasons, while NextEra Energy and Home Depot have entered the Timely Ten as higher interest rates and company-specific uncertainties weigh on their share prices.
The Timely Ten tells us where valuation is becoming more attractive. Our next step is to determine whether the price weakness represents a temporary setback or a genuine deterioration in the business.
Quality determines what we want to own. Valuation helps us decide when to act.
DGI Scorecard
This Week’s Highlights
MP Wealth-Builder Model Portfolio (Canada)
Annualized Total Return: +17.19% since inception
Total Return (includes dividends): +16.83 % year-to-date
Dividend Growth: 7.0% year-to-date
Growth Yield: 3.2%
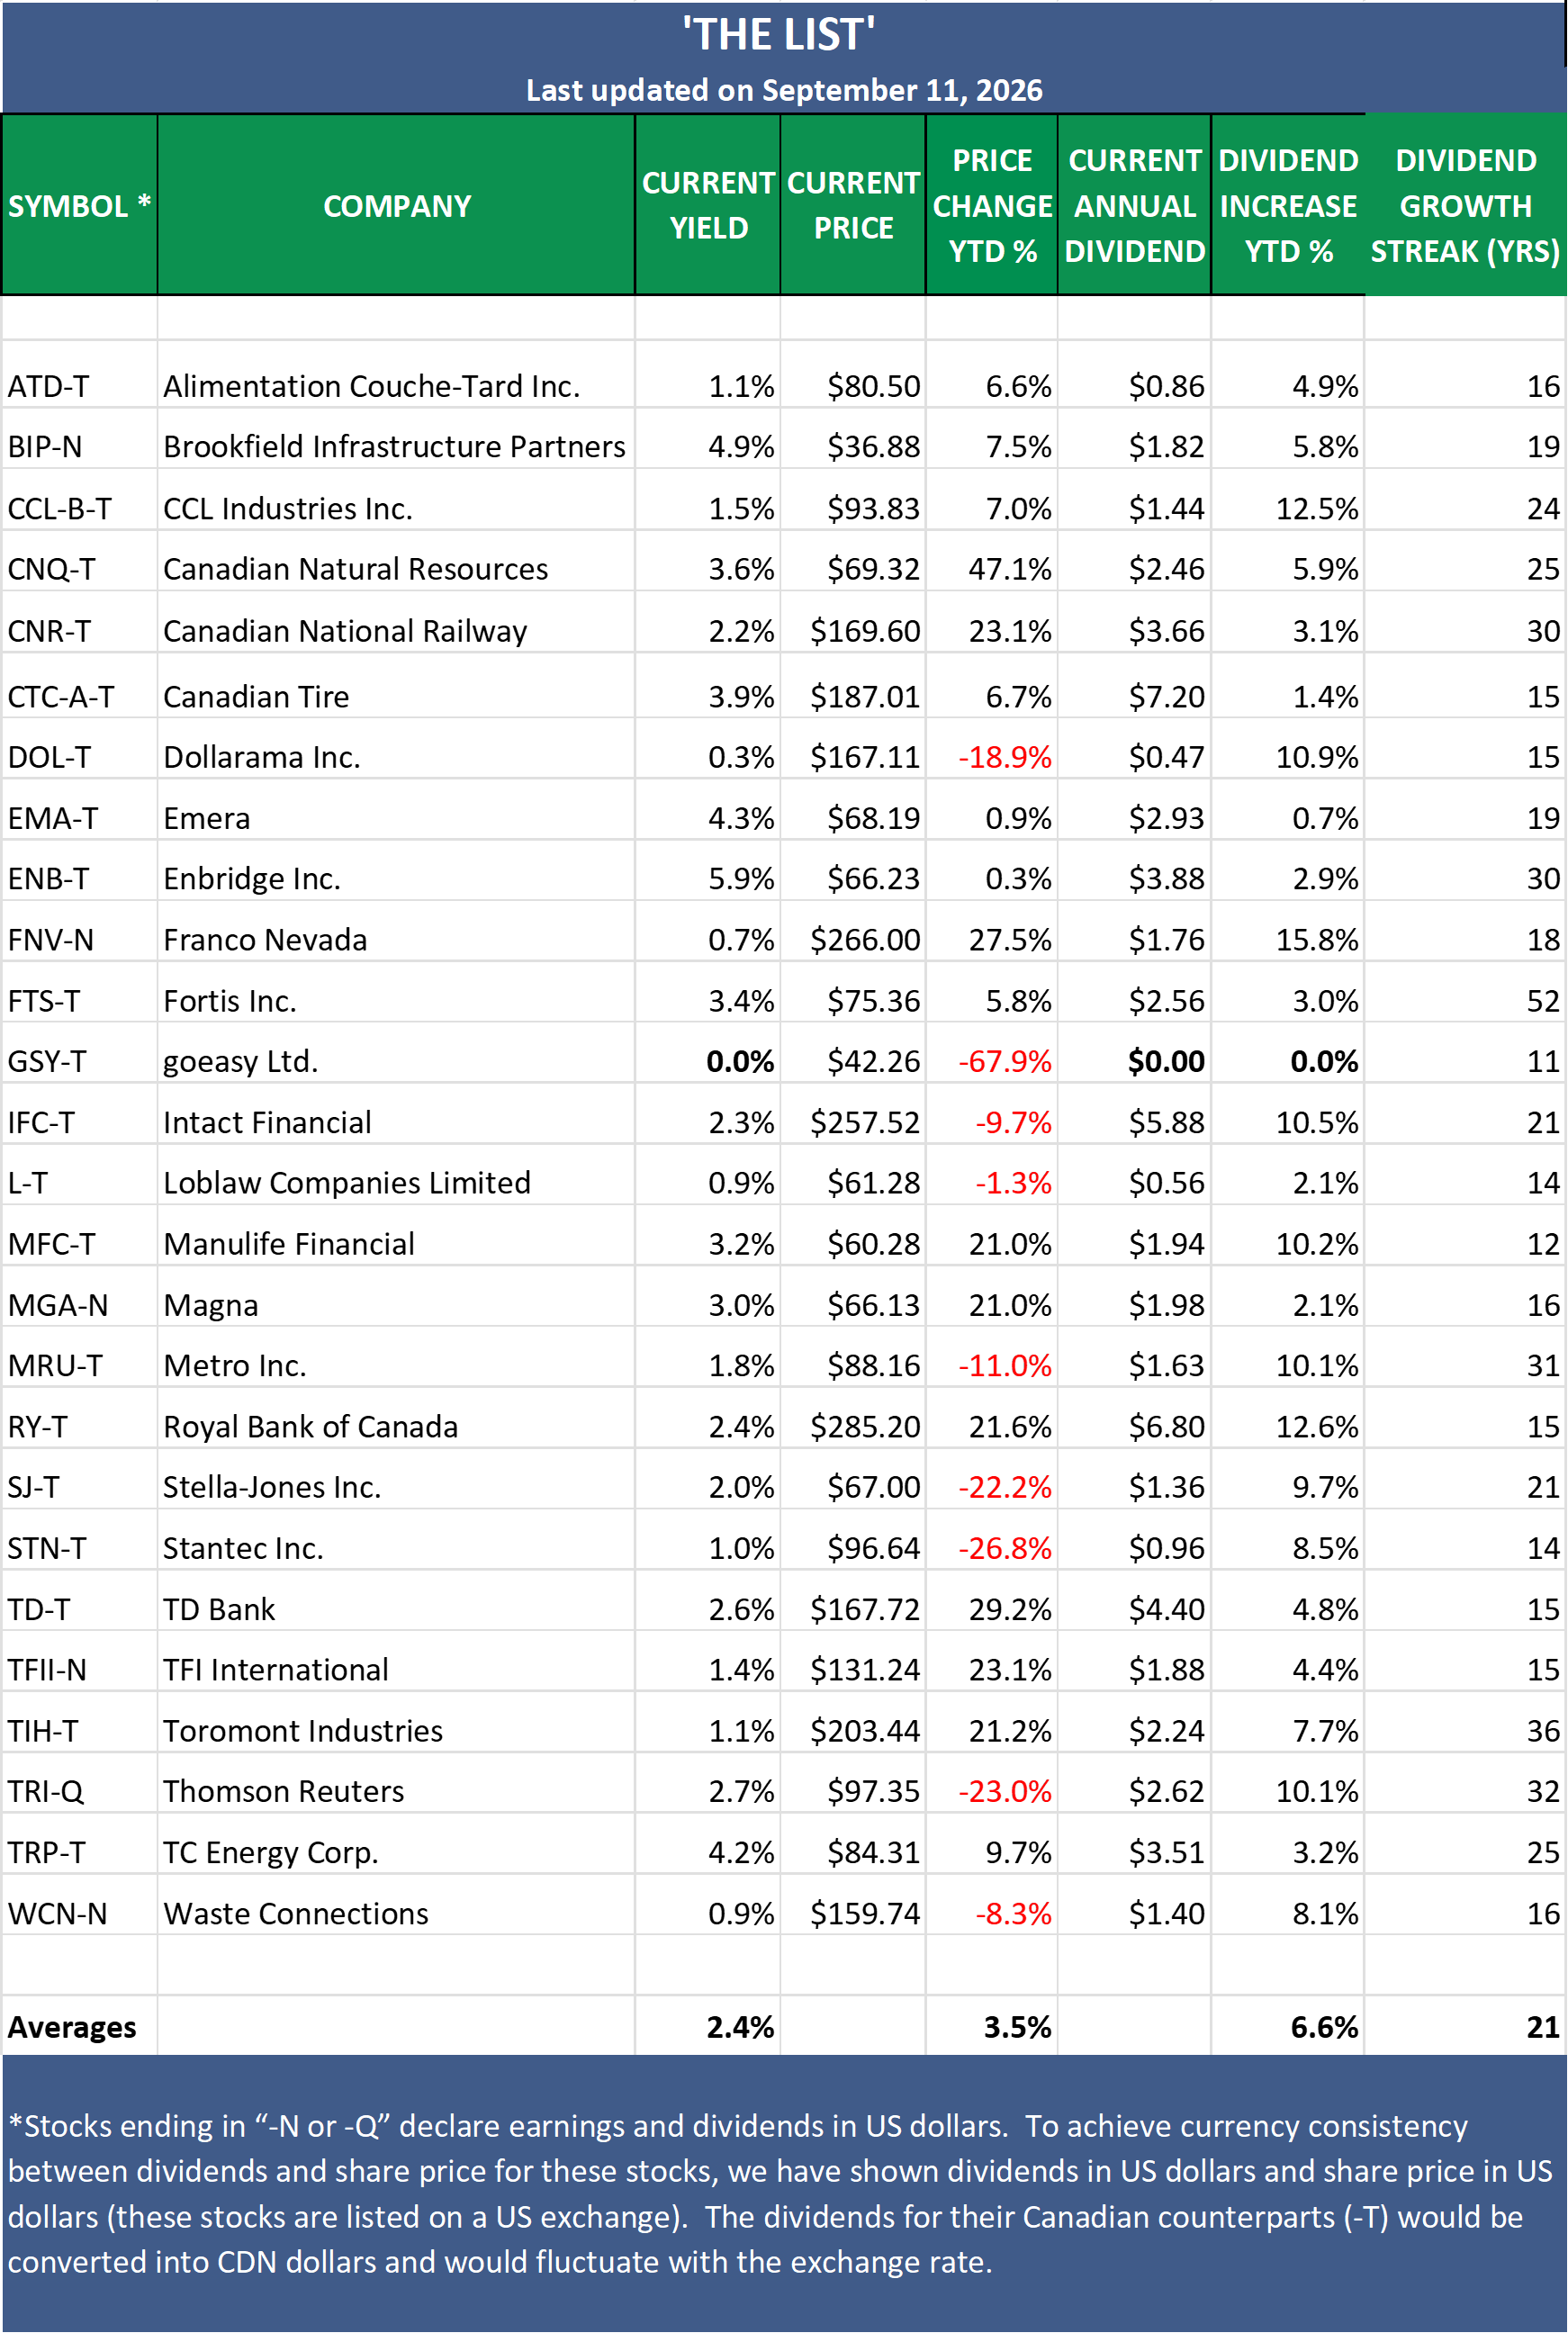
The List (Canada)
Dividend Income Growth: +6.6% year-to-date
Capital Appreciation: +3.5% year-to-date
Dividend Announcements Last Week: None
Earnings Reports Last Week: None
Earnings Reports This Week: One
Top Performers Last Week:
Toromont Industries (TIH-T), up +2.56%.
Franco Nevada (FNV-N), down -0.07%.
TD Bank (TD-T), down -0.31%.
Worst Performer Last Week:
Thomson Reuters (TRI-Q), down -7.88%.
Watchlists
The Magic Pants 2026 list (The List) includes 26 Canadian dividend growth stocks, and our new American watchlist (The List-USA) contains 28 companies. Here are the criteria to be considered a candidate on our watchlists:
Dividend growth streak: 10 years or more.
Market cap: Minimum one billion dollars.
Diversification: Limit of five companies per sector, preferably two per industry.
Cyclicality: Exclude REITs and pure-play energy companies due to high cyclicality.
Based on these criteria, companies are added or removed from The List annually on January 1. Prices and dividends are updated weekly.
The watchlists are not a portfolio but a coaching tool that helps us think about ideas and manage risk in our model portfolio. We own some, but not all, of the companies on these watchlists. In other words, we might want to buy these companies when valuation looks attractive.
Our newsletter provides readers with a comprehensive insight into the implementation and advantages of our dividend growth investing strategy. This evidence-based, unbiased approach empowers DIY investors to outperform both actively managed dividend funds and passively managed indexes and dividend ETFs over longer-term horizons.
In the last week of every month, I will show the updated watchlist for our American dividend growers (The List-USA). I will show the watchlist after the Canadian watchlist above.
New to Magic Pants?
Magic Pants Dividend Growth Investing is a behind-the-scenes look at how we build, maintain, and improve a dividend growth portfolio using real money, real positions, and real results.
Our objective is to grow dividend income by 7-10%+ annually while achieving long-term capital appreciation that matches or exceeds the broader market over a full investing cycle.
The name comes from a simple idea: when a quality company pays a dividend, cash moves from the company’s pocket to yours while your ownership stake remains intact. As earnings and dividends grow, the compounding cycle can accelerate. That’s the magic.
Build Your Own Growing Income Machine
Looking for a helping hand in the market? Members of Magic Pants Dividend Growth Investing receive exclusive ideas and guidance designed to help navigate changing market conditions.
The Magic Pants model portfolios (Canadian and American) are real-money, dividend-growth portfolios funded with actual capital and executed in live accounts. We own, size, and track every position in real time using our disciplined DGI process.
Become a paid subscriber and see exactly how we put the process into practice. You’ll also receive full access to this post and exclusive subscriber-only content.
We do the work. You stay in control.
From breaking news and quarterly earnings to the latest dividend announcements, we highlight what matters most and explain what it means for dividend growth investors.
