


A falling share price can signal opportunity or trouble.
Welcome to this week’s MP Market Review, where we put our dividend growth investing (DGI) process into practice with real money, real positions, and real results.
The TSX has gone virtually nowhere over the past 30 days, while the S&P 500 has gained about 2% even though ten of the index's eleven sectors declined. Beneath the surface, weakness is creating opportunities for selective dividend growth investors. Rising bond yields and slowing growth have pushed several quality businesses toward historically attractive valuations.
The hard part is knowing when a company is sensibly priced versus a value trap. Our Timely Ten lists help zero in on opportunities, and then our process takes over.
IN THIS ISSUE: DGI Clipboard • DGI Scorecard • DGI News • DGI Updates • Earnings Releases
DGI Clipboard
“Current yield, using its own historic yield as a guide, is, in my view, a fine valuation measure.”
— Tom Connolly
Timely Ten: We Found Opportunities. We Also Found Reasons to Wait.
Timely Ten Update
The markets may be telling two different stories, but beneath the surface, the message for dividend growth investors is remarkably similar: opportunities are emerging, but selectivity matters more than ever.
Over the past 30 days, the TSX has barely moved, while the S&P 500 has gained about 2%. Yet both markets are showing considerable weakness beneath their headline returns. Rising bond yields, inflation concerns and slowing growth have pressured many traditional dividend-paying businesses, pushing some valuations toward historically attractive levels.
This month’s Canadian and American Timely Ten lists reflect that divergence. Couche-Tard and Zoetis retain their respective #1 rankings, although both face questions about future earnings growth. Meanwhile, Waste Connections, Stella-Jones, and NextEra Energy have presented compelling opportunities for us to put additional capital to work. Others, including Comcast, Intact Financial and Home Depot, warrant closer attention as their share prices retreat.
The challenge is separating temporary valuation weakness from deteriorating business fundamentals. Our Timely Ten identifies where to look. Our research determines where to invest.
How We Rank the Timely Ten
Each month, we rank every company on our Canadian and U.S. watchlists by the discount between its current market price and its estimated fair value, using Dividend Yield Theory.
The calculation is straightforward:
Fair Value = Current Annual Dividend ÷ Historical High Dividend Yield
The larger the discount to estimated fair value, the higher the company ranks.
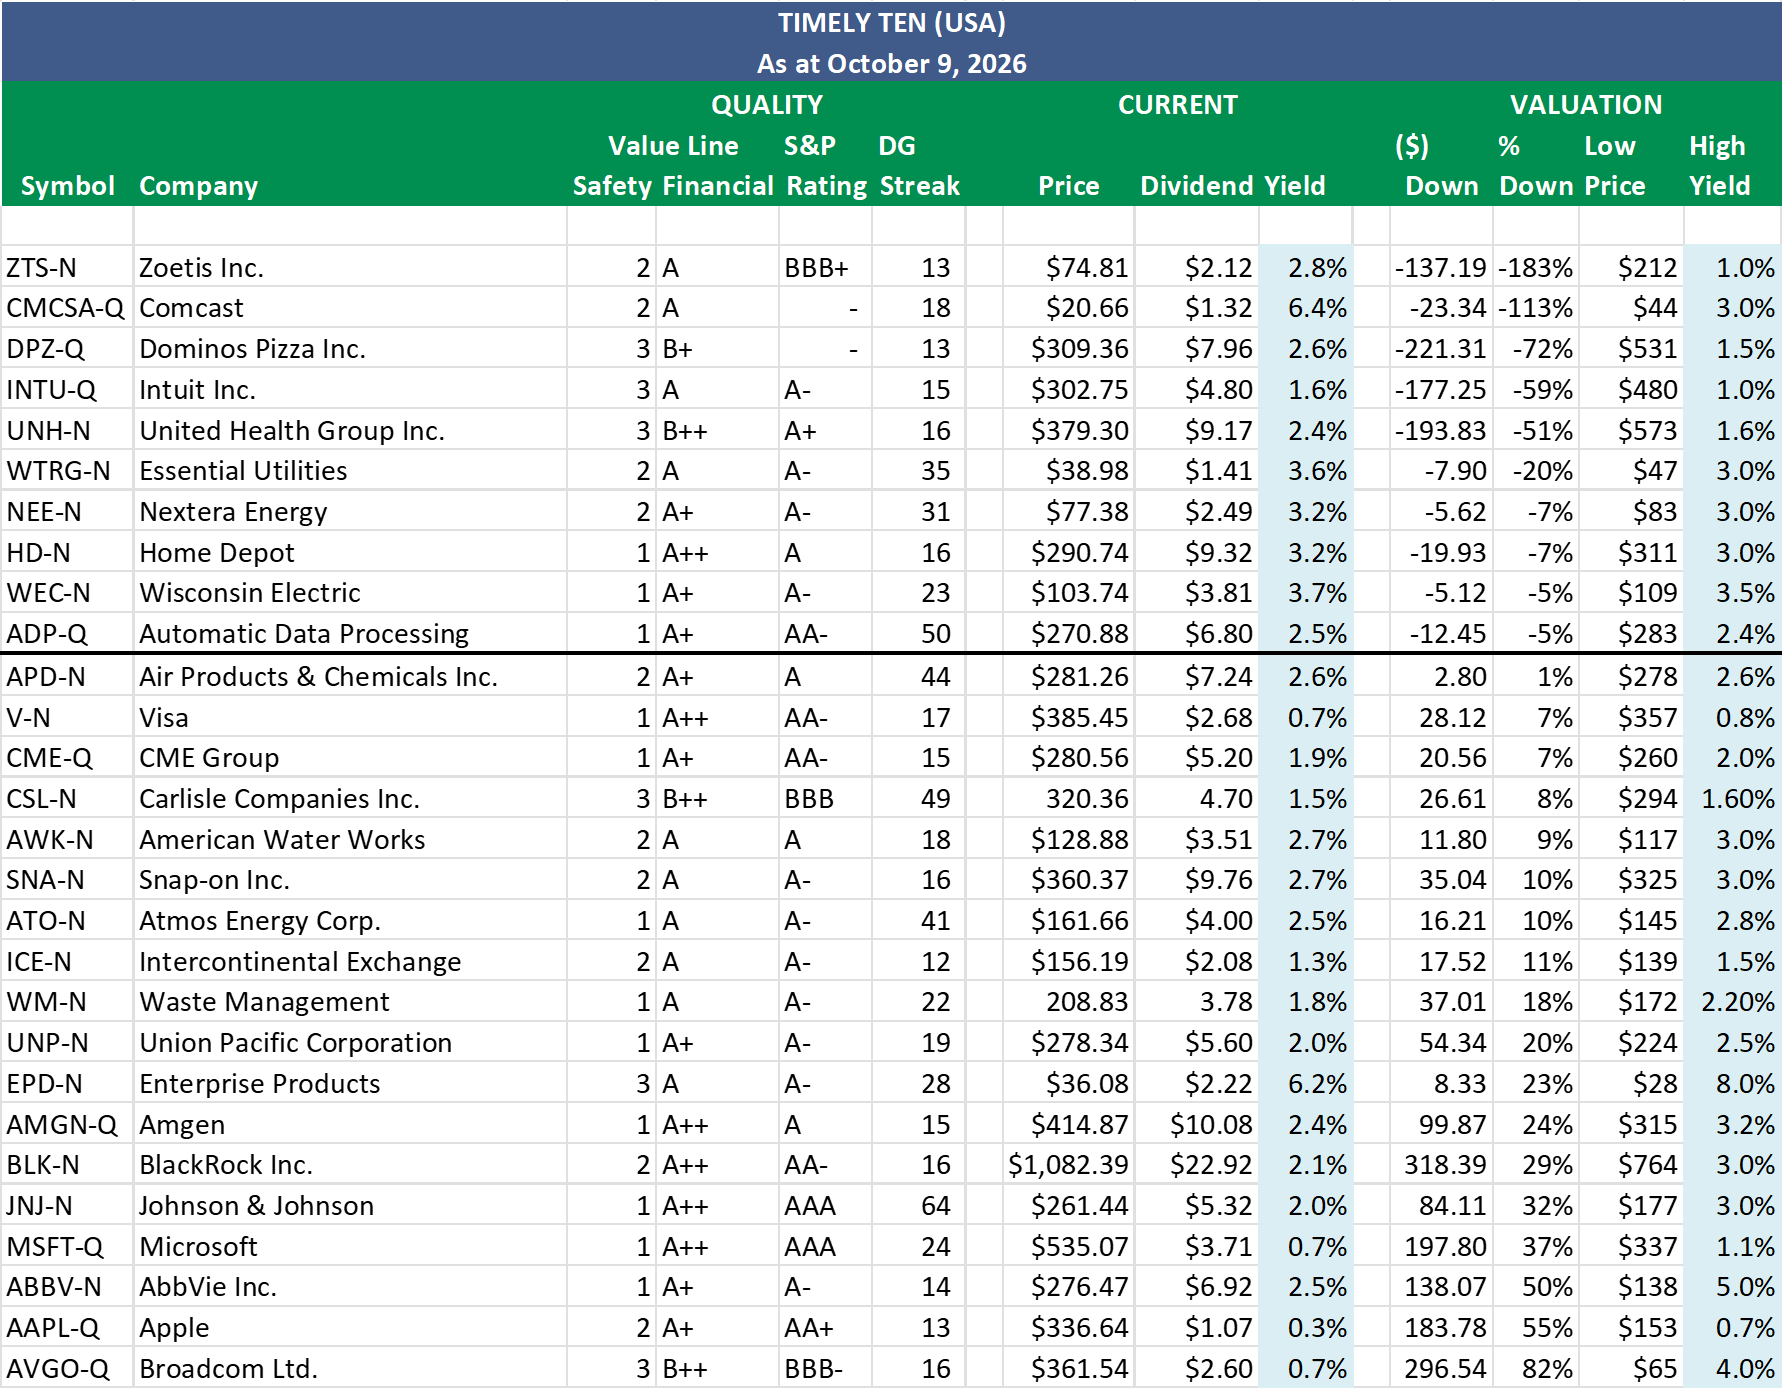
The ten companies above the thick black line represent the most undervalued stocks on our watchlists, as ranked by Dividend Yield Theory. While not all may be trading below their estimated fair values, they currently offer the most attractive valuations relative to their historical dividend yields.
These are our Timely Ten.
No valuation method is perfect, but Dividend Yield Theory has proven an effective way to identify attractive entry points into high-quality dividend growth companies. Combined with our quality-first investment process, it helps us deploy capital more disciplinedly and removes much of the emotion from our decisions.
The Timely Ten is not an automatic buy list. It is a starting point for further research.
Canadian Timely Ten
The TSX has gone virtually nowhere over the past 30 days, but important shifts are taking place beneath the surface.
Rising bond yields have weighed on traditional dividend-paying sectors, particularly telecoms and utilities, while technology has emerged as an unusual source of strength. Even higher commodity prices haven't consistently translated into stronger energy and materials stocks.
For dividend growth investors, this is where discipline matters most.
We are not trying to predict the next move in interest rates or the broader market. We focus on identifying quality businesses with sustainable, growing dividends that trade at sensible valuations.
When share prices fall faster than business fundamentals deteriorate, opportunities begin to emerge.
The upcoming third-quarter earnings season should help separate genuine deterioration in business fundamentals from temporary valuation pressures. That distinction will matter most for several companies on this month’s Timely Ten.
#1 Alimentation Couche-Tard (ATD)
Couche-Tard holds firmly to the top spot on our Timely Ten, and it became even more attractively priced after another 3.5% decline this month.
The company remains a quality dividend growth business, but investors are increasingly questioning its near-term growth prospects.
Management needs to show stronger organic growth and execute its expansion strategy successfully. If it delivers, today’s depressed valuation could prove to be an attractive entry point for long-term investors.
Until then, further valuation compression remains a risk. A great business is not automatically a great investment at any price.
#2 Waste Connections (WCN)
The recent share-price weakness caught our attention, prompting a deeper review of the company’s fundamentals, dividend growth prospects and valuation.
We liked what we found and decided to add to our existing position.
Subscribers can read the research behind that decision in our September 29 newsletter, Inside Our Process: How a Stock Earns a Place in Our Portfolio.
#3 Stella-Jones (SJ)
Stella-Jones climbs another two positions this month, moving from #5 to #3.
Like Waste Connections, Stella-Jones recently caught our attention because its share price offered an opportunity to revisit its valuation.
Our research reinforced our confidence in the company’s long-term dividend growth prospects, so we added to our position.
Two companies moving up our Timely Ten. Two opportunities to put additional capital to work.
#5 Canadian Tire (CTC.A)
Canadian Tire slips three positions, from #2 to #5, as its share price strengthens.
The stock is now up approximately 10% year-to-date and continues to offer an above-average starting dividend yield.
However, dividend growth remains the sticking point.
With dividend growth averaging just 1.4% over the past few years, Canadian Tire has yet to demonstrate the income growth characteristics we prefer.
A generous starting yield is attractive, but without meaningful dividend growth, the long-term compounding potential is limited.
For now, we remain on the sidelines.
Worth Watching: Enbridge, Magna and Intact Financial
The bottom three positions on our Timely Ten, Enbridge, Magna and Intact Financial, also deserve further research.
Of the three, Intact Financial (IFC) is particularly interesting.
Its share price has fallen another 6% since our last Timely Ten update, raising an important question: Is the market simply adjusting the valuation of a quality business, or are investors anticipating a more persistent deterioration in earnings?
The next important checkpoint is November 3, 2026, when Intact is scheduled to report third-quarter earnings.
That report should provide greater clarity on underwriting performance, profitability and the company’s earnings outlook.
If fundamentals remain sound, the recent decline could present an opportunity. If earnings expectations continue to weaken, patience may be warranted.
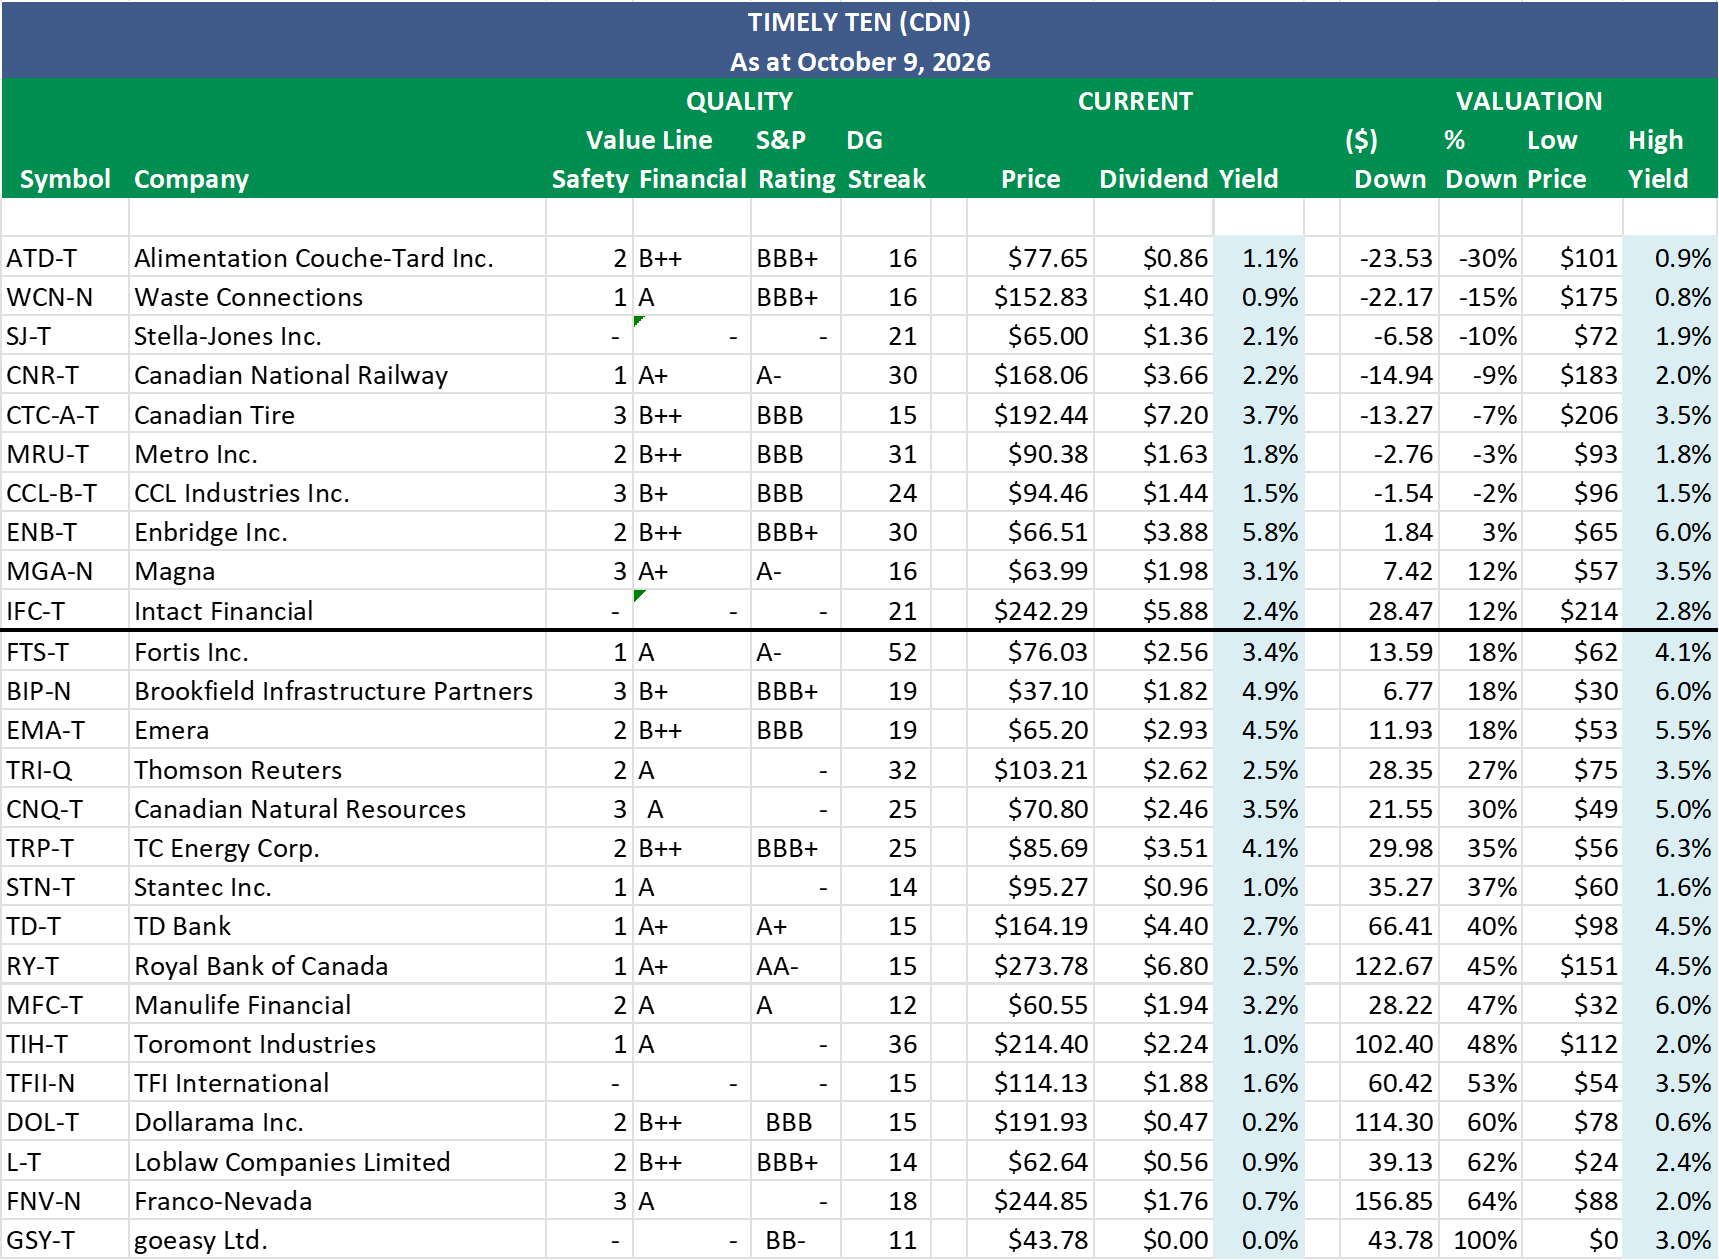
Note: goeasy Ltd.’s dividend has been suspended so we have moved it to the bottom of the list.
American Timely Ten
The S&P 500 has gained approximately 2.0% over the past 30 days, closing October 9 at 7,811.54, just shy of its recent record high. But like the TSX, the headline index masks considerable weakness beneath the surface.
Technology continues to lead the market, fueled by enthusiasm for artificial intelligence and strong earnings growth. Meanwhile, rising bond yields, higher energy prices and renewed inflation concerns have pressured several traditional dividend-paying sectors, particularly financials, real estate and utilities.
September was especially challenging. Ten of the eleven S&P 500 sectors declined, with technology the lone bright spot. The first full week of October brought some relief, as utilities, consumer staples and energy rebounded while technology took a breather.
For dividend growth investors, the divergence is worth watching. While technology continues to drive index returns, weakness elsewhere is bringing some quality dividend growers' valuations closer to historically attractive levels. The opportunity is to distinguish between companies facing temporary headwinds and those experiencing a more fundamental deterioration in their businesses.
#1 Zoetis (ZTS)
Zoetis remains at the top of our Timely Ten, but its continued share-price weakness is becoming increasingly difficult to ignore.
The company remains a leader in animal health, with valuable brands, attractive margins, and a strong dividend-growth history. However, slowing demand in its U.S. companion animal business, increasing competition, and lower earnings expectations suggest a recovery may take longer than previously anticipated.
The lower share price has made Zoetis look increasingly attractive on historical valuation measures. But a falling price alone does not make a stock a bargain.
The company’s focus remains on stabilizing sales, defending market share and restoring earnings growth. Until we see evidence of improvement, patience is warranted. That's why our process puts quality first and valuation second.
#2 Comcast (CMCSA)
Comcast continues to trade at a historically depressed valuation, but the market has legitimate reasons to be skeptical.
Intensifying competition from fibre-optic and fixed wireless providers is eroding broadband subscribers, pressuring earnings and raising questions about the company’s long-term growth prospects.
Comcast continues to generate substantial free cash flow, which supports its dividend. However, maintaining that dividend is one thing. Delivering the sustainable dividend growth we seek is another.
At today’s valuation, Comcast could represent a compelling opportunity, but the risk of a value trap remains. We want to see broadband subscriber losses moderate, operating margins stabilize and earnings growth resume before becoming more aggressive.
#7 NextEra Energy (NEE)
NextEra Energy climbed two positions in our Timely Ten this month, moving from #9 to #7.
Following additional research, we decided to increase our position in this quality dividend grower.
Rising bond yields have pressured utility valuations, and NextEra is no exception. Higher interest rates can also increase financing costs for capital-intensive businesses, making the current environment challenging for the sector.
But our investment thesis focuses on the company’s long-term earnings and dividend growth potential, not short-term interest-rate movements.
We particularly like NextEra’s dividend return profile. Its reasonable starting yield and strong historical dividend growth offer the potential for an increasingly attractive income return on our original investment over time.
We are comfortable being patient while the business continues to grow its earnings and dividends. As we like to say, dividends lead, prices follow.
#8 Home Depot (HD)
Home Depot is becoming increasingly interesting as its share price continues to retreat.
At about 19 times forward earnings and a dividend yield near 3.3%, the stock trades at a more attractive valuation relative to its historical norms. Its dividend yield is now roughly one percentage point above its 15-year average.
Unlike Zoetis and Comcast, where competitive pressures raise more fundamental questions about future growth, Home Depot’s challenges appear largely cyclical.
Elevated mortgage rates, sluggish housing turnover and cautious consumer spending have weighed on demand for home improvement projects. These conditions have slowed earnings growth and compressed the company’s valuation.
Yet Home Depot remains a dominant retailer with strong cash generation, a durable competitive position and a long history of rewarding shareholders through growing dividends.
The key risk is timing. Mortgage rates could remain elevated longer than expected, delaying a recovery in housing activity and renovation spending.
For patient dividend-growth investors, however, this may be an opportunity to buy a quality business at a sensible valuation while waiting for the housing cycle to improve.
The Takeaway
A falling share price can create an opportunity, but it can also be a warning. That distinction runs through both Timely Ten lists this month. Some companies face cyclical pressures, while others face more fundamental questions about competition, profitability, and future growth. We have acted where our research supports the investment case, adding to Waste Connections, Stella-Jones and NextEra Energy. Elsewhere, we are content to remain patient. An attractive valuation matters only if the underlying business can keep growing earnings and dividends.
The upcoming earnings season should help clarify which companies are experiencing temporary setbacks and which may require a reassessment of their long-term prospects. In the meantime, our approach remains unchanged: quality first, valuation second, and monitor continuously. We are not trying to predict market bottoms or chase the highest yields. We build portfolios of quality businesses that can deliver growing dividend income and capital appreciation over time. When the fundamentals remain intact, and prices become attractive, we are prepared to act.
Quality determines what we want to own. Valuation helps us decide when to act.
DGI Scorecard
MP Wealth-Builder Model Portfolio (Canada)
Annualized Total Return: +17.19% since inception
Total Return (includes dividends): +16.83 % year-to-date
Dividend Growth: 7.0% year-to-date
Growth Yield: 3.2%
(Inception May 1, 2022, to July 31, 2026. Returns are actual results of our model portfolio in CAD with dividends reinvested.)
This Week’s Highlights
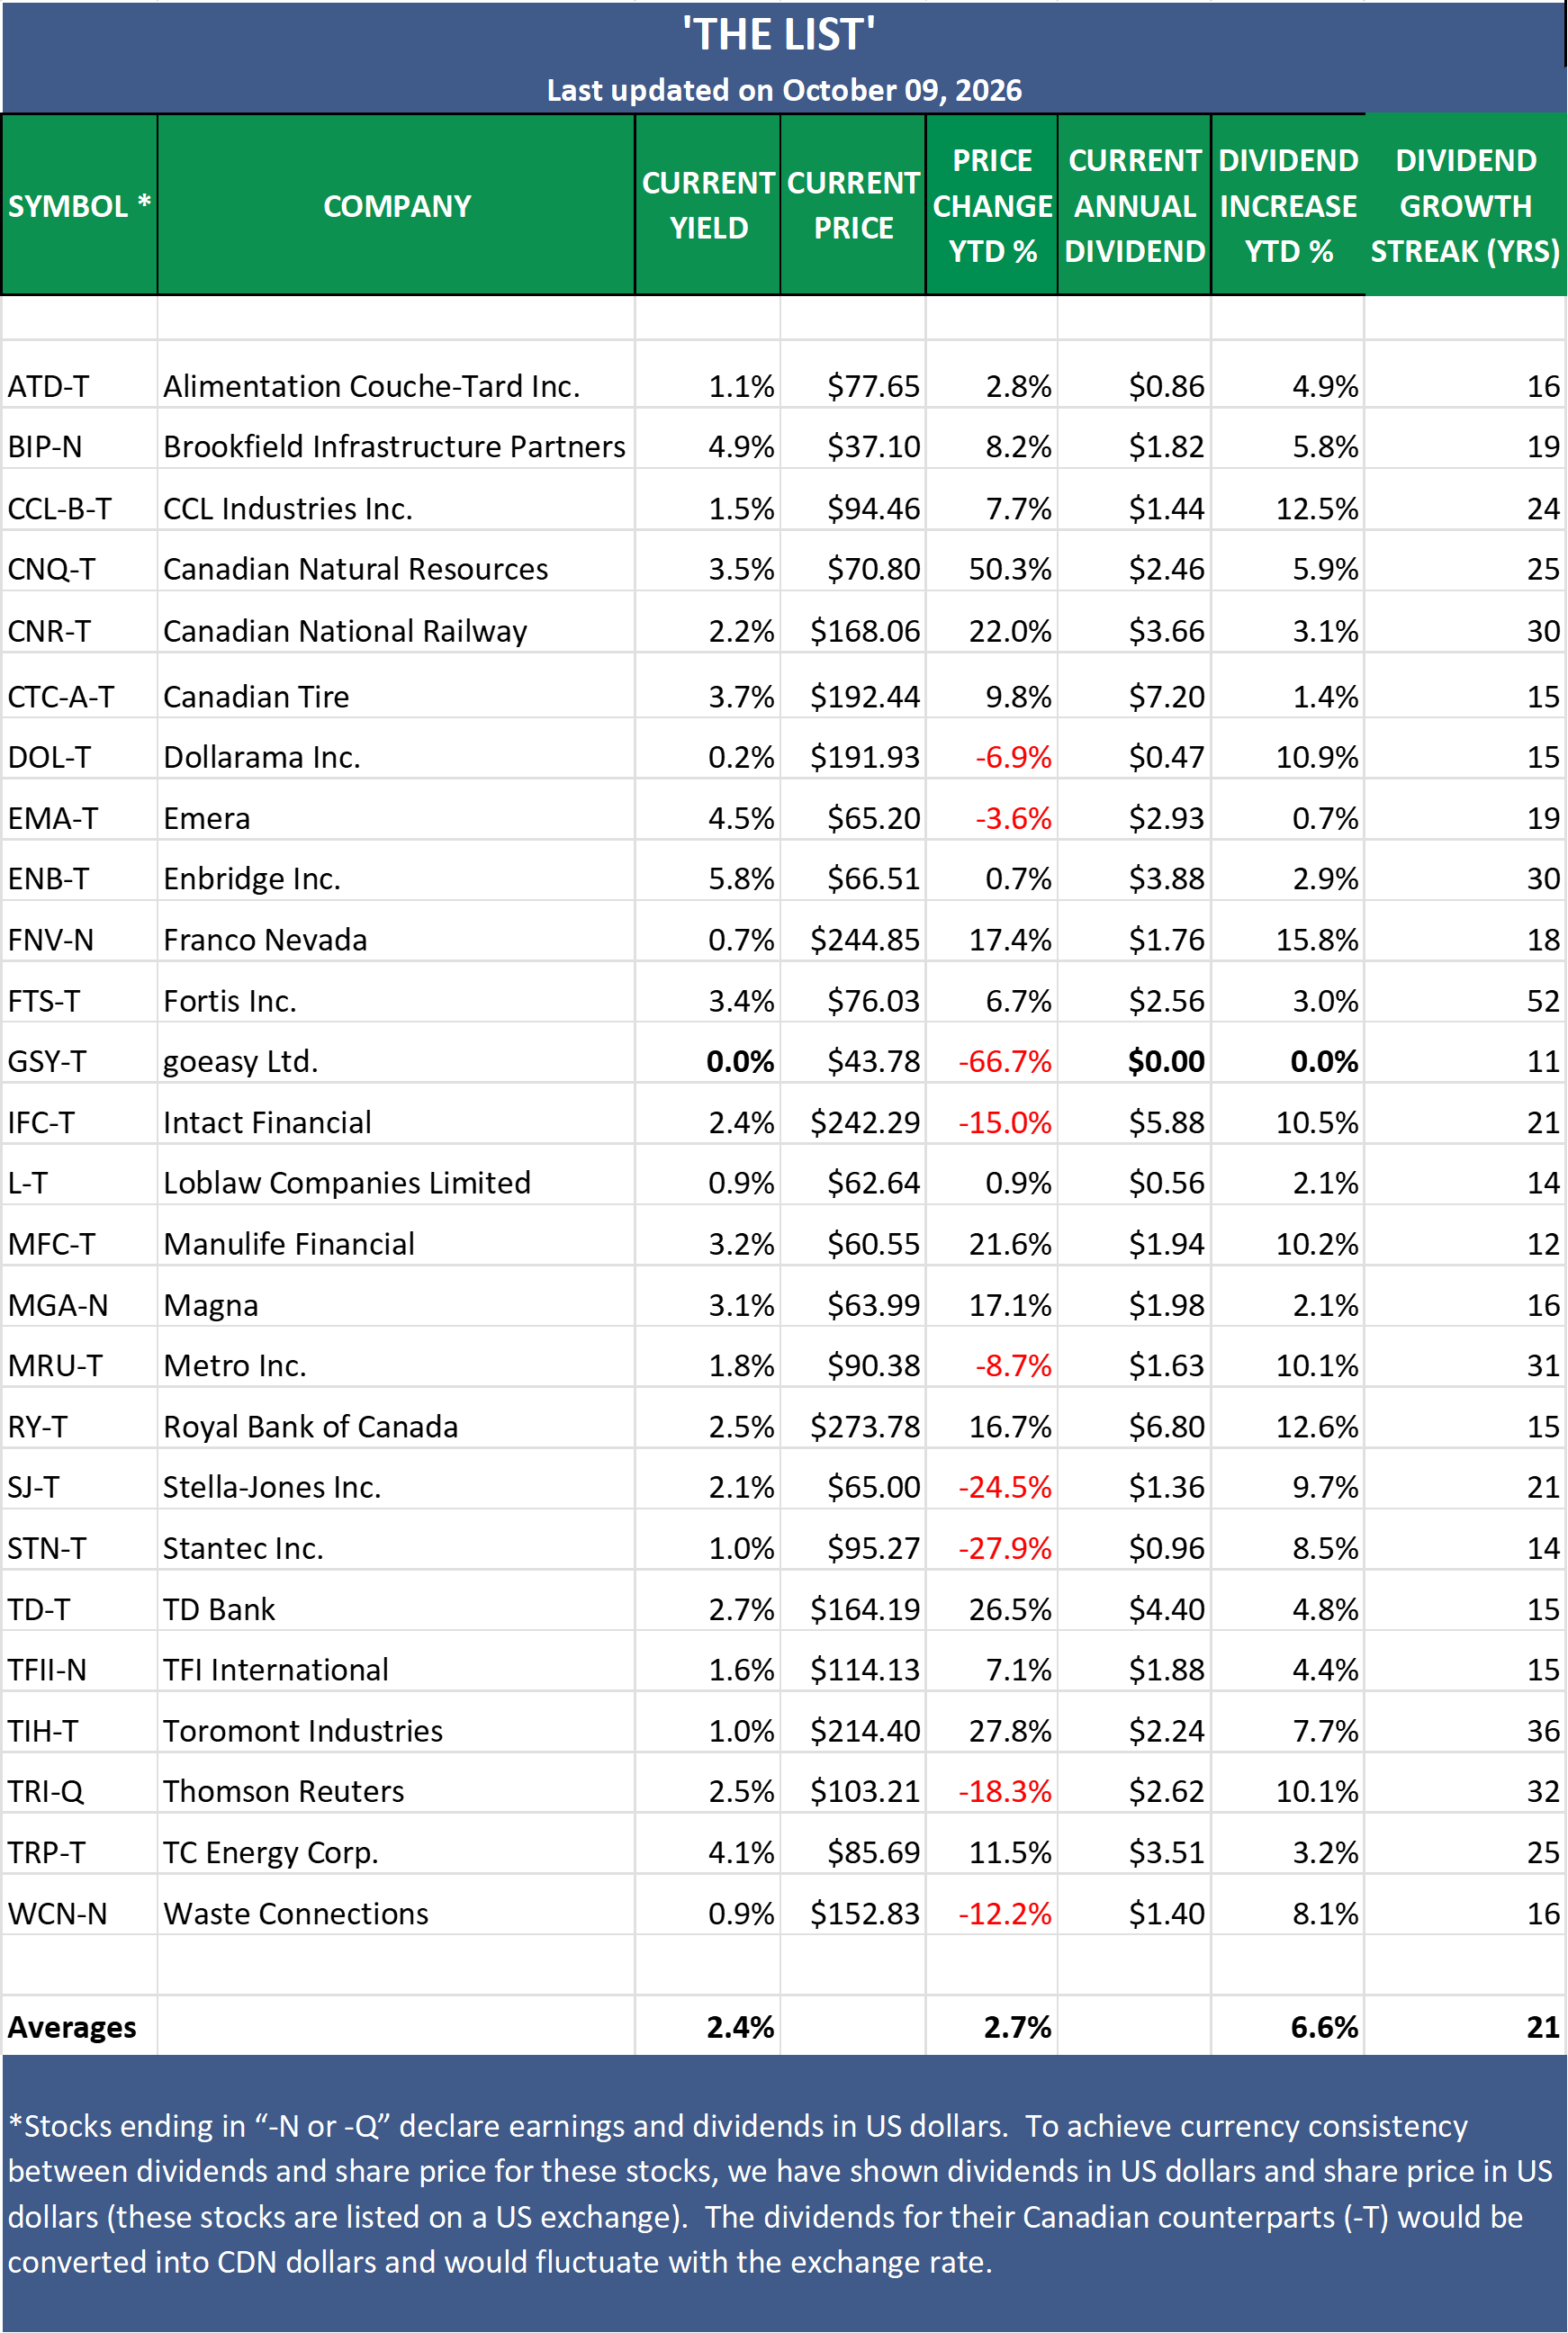
The List (Canada)
Dividend Income Growth: +6.6% year-to-date
Capital Appreciation: +2.7% year-to-date
Dividend Announcements Last Week: None
Earnings Reports Last Week: None
Earnings Reports This Week: None
Top Performers Last Week:
Thomson Reuters (TRI-Q), up +5.73%.
Dollarama Inc. (DOL-T), up +4.34%.
Canadian Natural Resources (CNQ-T), up +2.46%.
Worst Performer Last Week:
Toromont Industries (TIH-T), down -9.42%.
Watchlists
The Magic Pants 2026 list (The List) includes 26 Canadian dividend-growth stocks, and our new American watchlist (The List-USA) includes 28 companies. Here are the criteria to be considered a candidate on our watchlists:
Dividend growth streak: 10 years or more.
Market cap: At least $1 billion.
Diversification: Limit of five companies per sector, preferably two per industry.
Cyclicality: Exclude REITs and pure-play energy companies due to high cyclicality.
Based on these criteria, we add or remove companies from The List annually on January 1. Prices and dividends are updated weekly.
The watchlists are not a portfolio but a coaching tool that helps us think about ideas and manage risk in our model portfolio. We own some, but not all, of the companies on these watchlists. In other words, we might want to buy these companies when valuation looks attractive.
Our newsletter provides readers with a comprehensive insight into the implementation and advantages of our dividend growth investing strategy. This evidence-based, unbiased approach has empowered DIY investors to outperform both actively managed dividend funds and passively managed indexes and dividend ETFs over longer-term horizons.
Each month, in the last week, I will share the updated watchlist for our American dividend growers (The List-USA). I will show the watchlist after the Canadian watchlist above.
New to Magic Pants?
Magic Pants Dividend Growth Investing is a behind-the-scenes look at how we build, maintain, and improve a dividend growth portfolio using real money, real positions, and real results.
Our objective is to grow dividend income by 7-10%+ annually while achieving long-term capital appreciation that matches or exceeds the broader market over a full investing cycle.
The name comes from a simple idea: when a quality company pays a dividend, cash moves from the company’s pocket to yours while your ownership stake remains intact. As earnings and dividends grow, the compounding cycle can accelerate. That’s the magic.
Build Your Own Growing Income Machine
Looking for a helping hand in the market? Paid members of Magic Pants Dividend Growth Investing get exclusive ideas and guidance to help them navigate changing market conditions.
The Magic Pants model portfolios (Canadian and American) are real-money, dividend-growth portfolios funded with actual capital and executed in live accounts. We own, size, and track every position in real time using our disciplined DGI process.
Become a paid subscriber and see exactly how we put the process into practice. You’ll also receive full access to this post and exclusive subscriber-only content.
We do the work. You stay in control.
From breaking news and quarterly earnings to the latest dividend announcements, we highlight what matters most and explain what it means for dividend growth investors.
